Belfius, Turning a Pension Number into a Plan People Can See
Client

How does a bank-insurer move from calculating a pension figure to helping someone actually understand it?
Belfius Insurance is the insurance arm of the Belfius Group, one of Belgium's major bank-insurers. It operates semi-independently within the group, with its own digital roadmap and the freedom to iterate outside the Bank's ecosystem. Its Pension & Care ambition is clear: stop showing up only at the moment of sale and become a trusted partner across the decades of a customer's retirement. The math they already handle well, through an existing pension planner. The unsolved part is desirability: getting people to engage with their pension at all.
That is where Nimble came in. We ran a focused desirability and design track to shape a new digital pension experience: validate it with real almost-retired customers and give the Pension & Care team a recommendation it could act on, before committing to a build.
That is where Nimble came in. We ran a focused desirability and design track to shape a new digital pension experience: validate it with real almost-retired customers and give the Pension & Care team a recommendation it could act on, before committing to a build.
opportunity
Belfius's perspective
The ambition is to shift from product push to a pension debate, becoming a lifelong simplifying partner instead of a provider that appears only at the sale.
The gap is motivation. People get a number but no reason to engage or act, and closing that gap is the real prize.
A past internal tool taught a hard lesson: an unexplained result reads as a black box and erodes trust.
Belfius Insurance operates semi-independently from the Bank, so alignment starts at the Insurance level, and the new tool is built outside the Bank's ecosystem for faster iteration.
The industry's perspective
A silver wave is coming: one in three 65-year-olds will live to 95, pensions must now stretch 30+ years, and roughly €6B in assets is released yearly.
Pensions are complex and intimidating, so people tend to avoid the topic entirely.
Consumer apps have set a new bar for proactive, visual, contextual experiences; pension tools still feel transactional by comparison.
Pension fintechs like Warren are targeting the same savings, activating dormant money and raising expectations; staying transactional risks losing that ground.
Correct calculations are table stakes now, the real contest is won on motivation, clarity, and guiding people to the right next step.
What the concept covers
A pension experience that explains and coaches, not just calculates
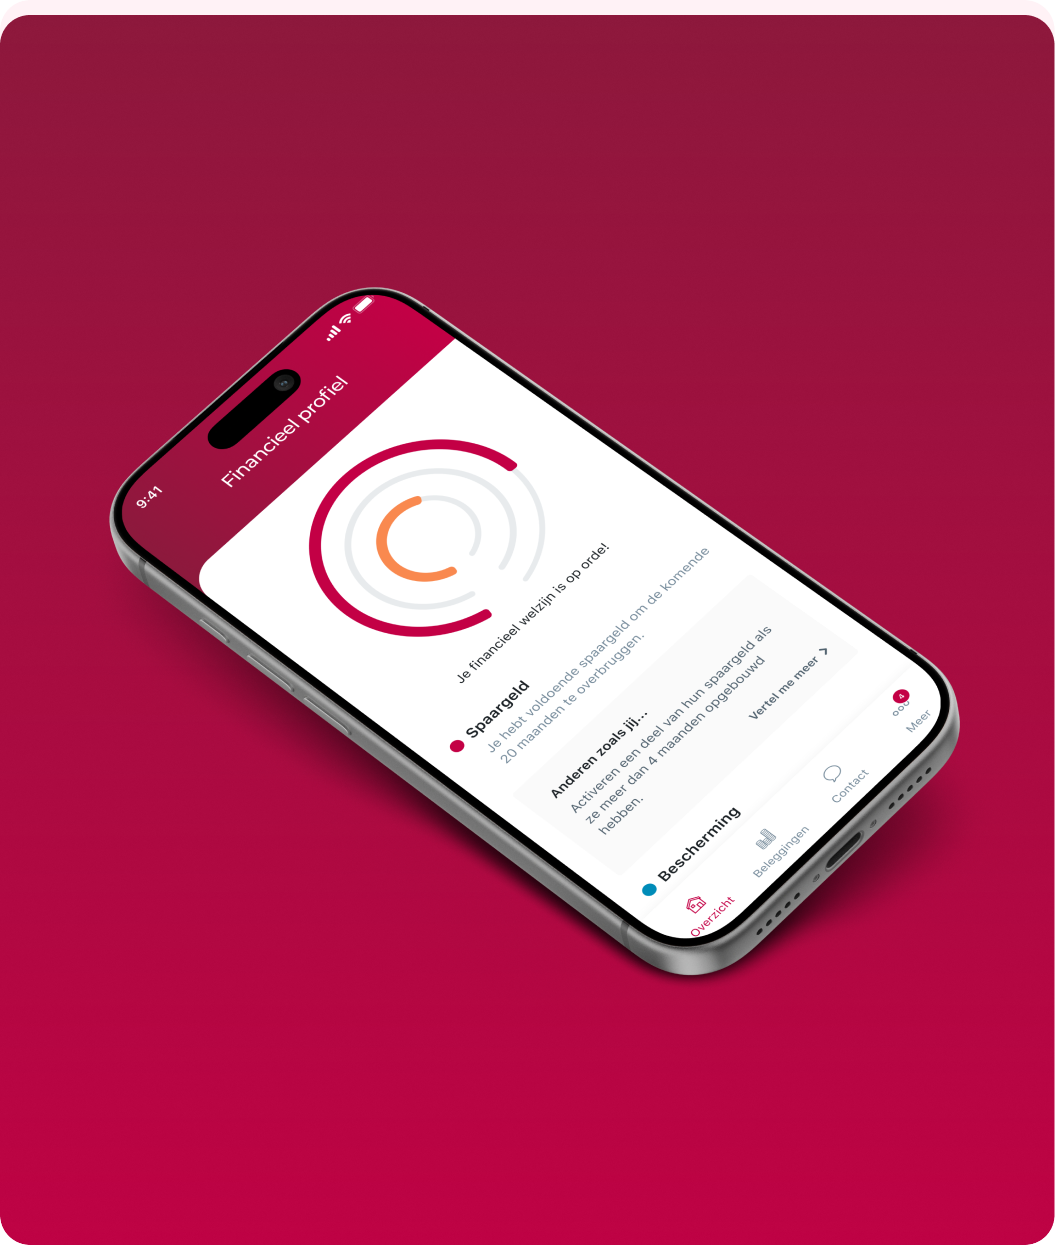
Coaching-first entry point
Starts from someone's goals and desired lifestyle instead of a blank data-entry form. It turns those inputs into a personal starting point, not a data request.
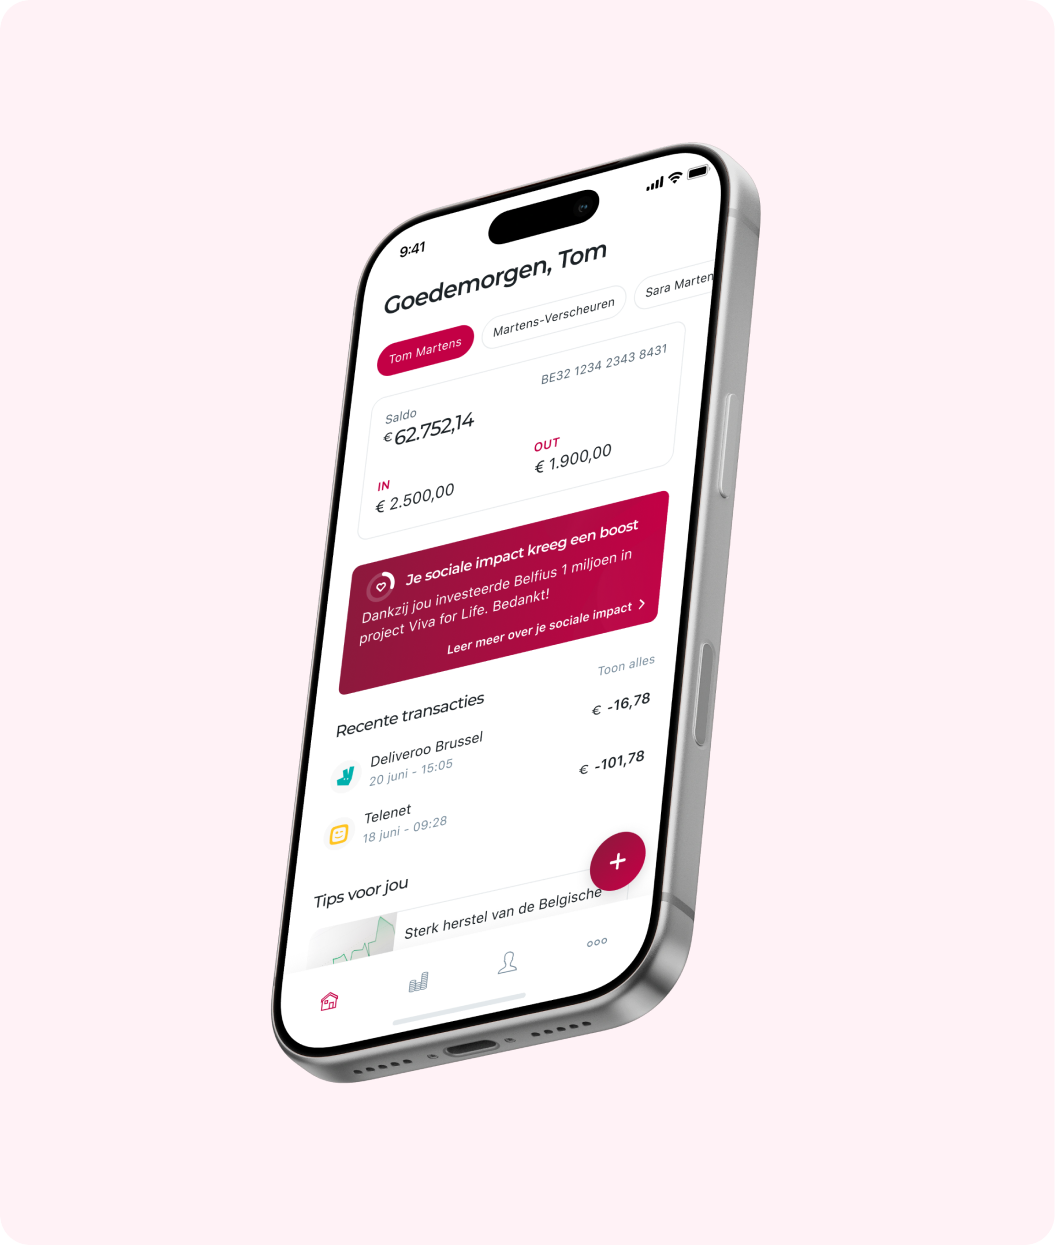
Coverage-ratio view
Shows the surplus or gap after the lifestyle someone wants, compared against their pension building blocks. It reframes "will I have enough?" into one answerable question: can I maintain my standard of living?
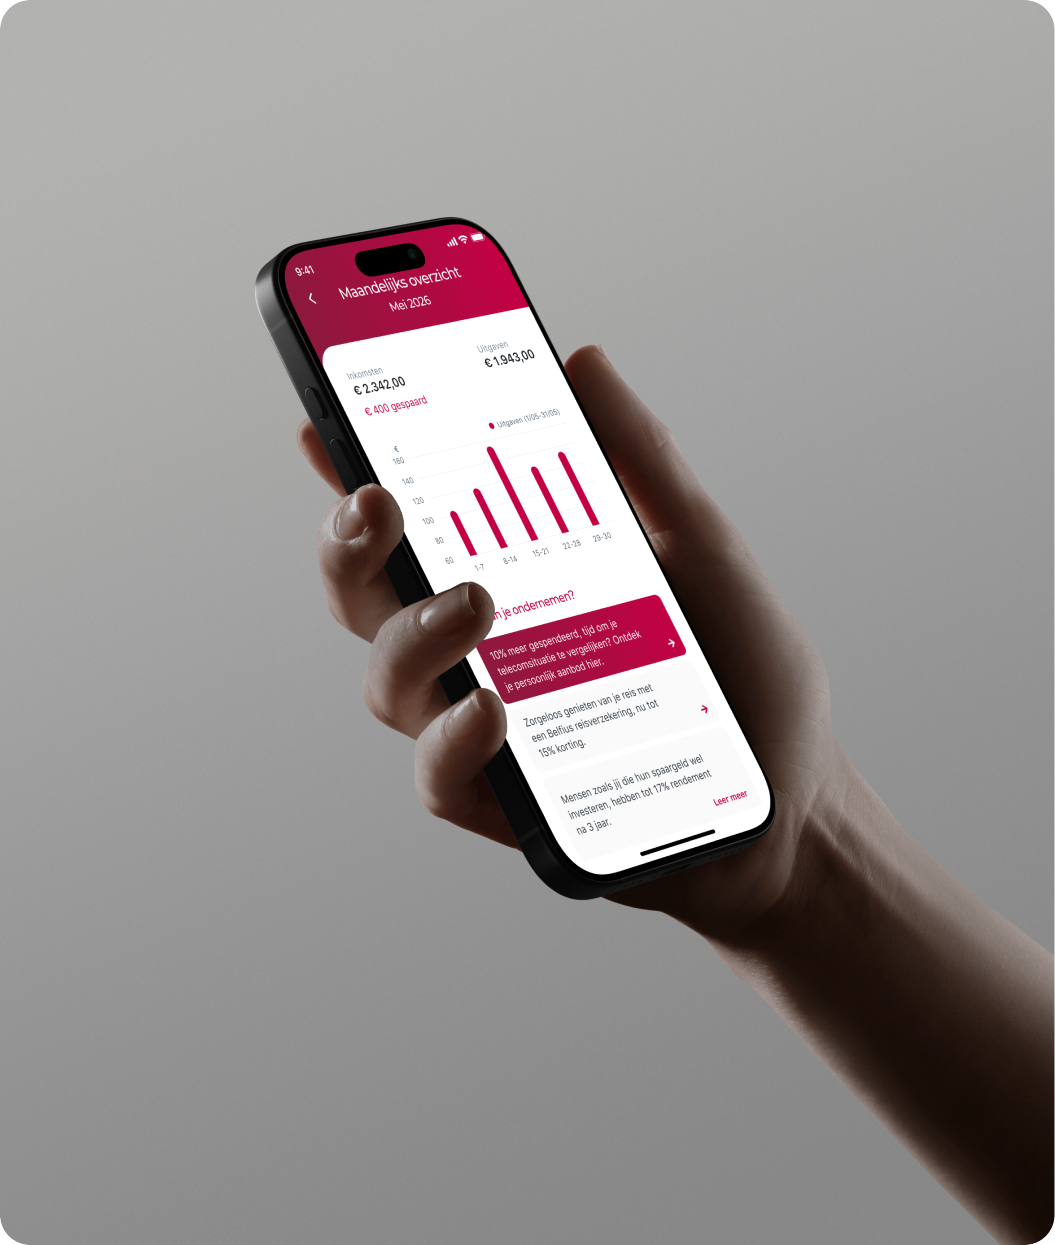
Visible reasoning behind the number
Living-expenses curves, life-expectancy assumptions, and the pension pillars are shown alongside the result. This makes the outcome feel grounded in Belfius's own data, not generated by a black box.
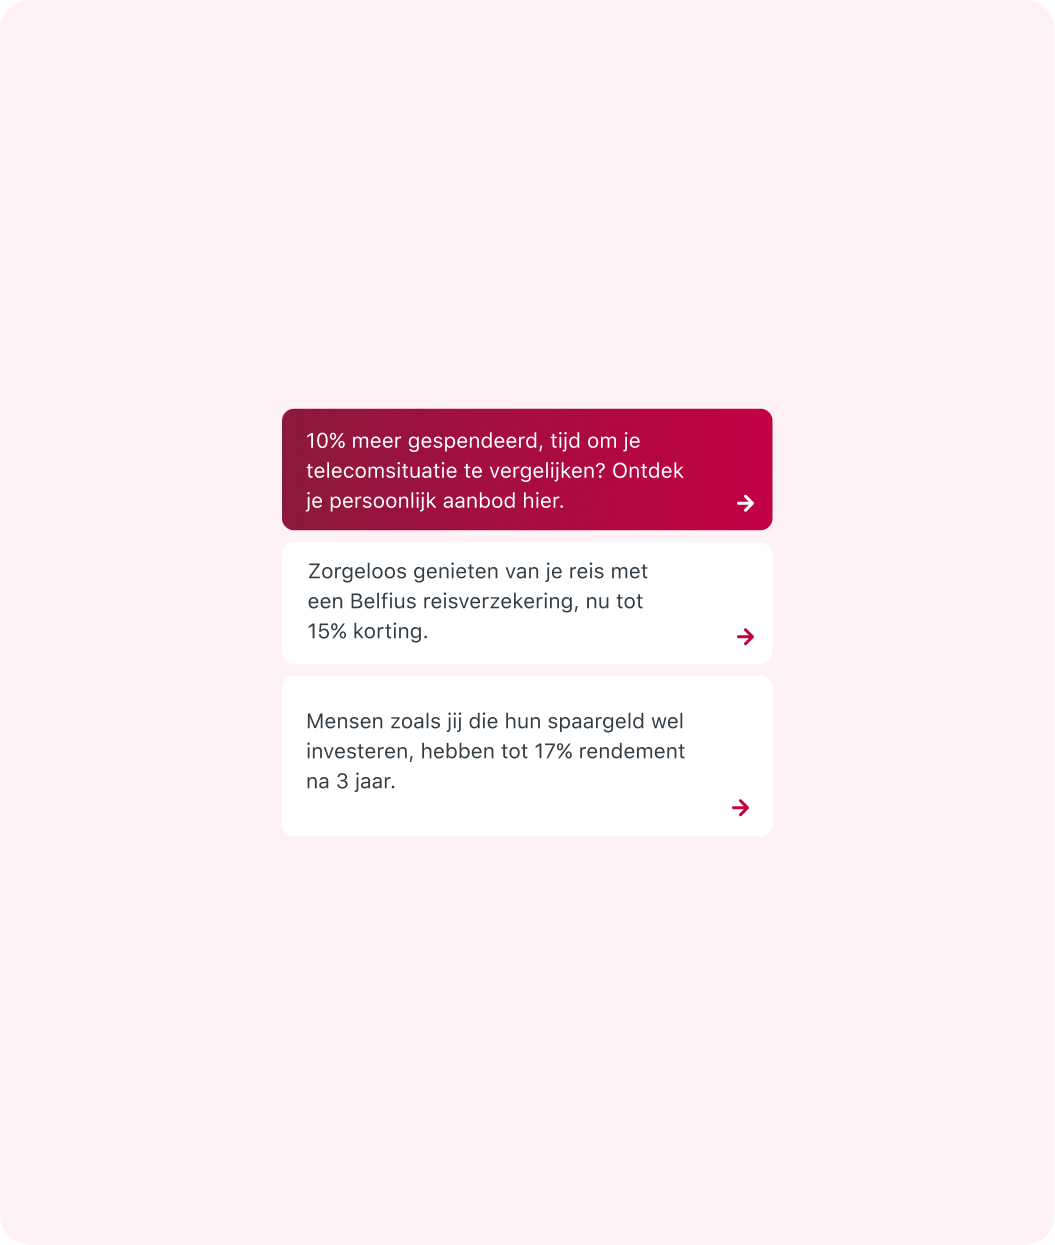
Micro-triggers for deeper exploration
Prompts like "why is my legal pension this?" or "what about my third pillar?" let people dig into specifics on demand. They build understanding without forcing it upfront.
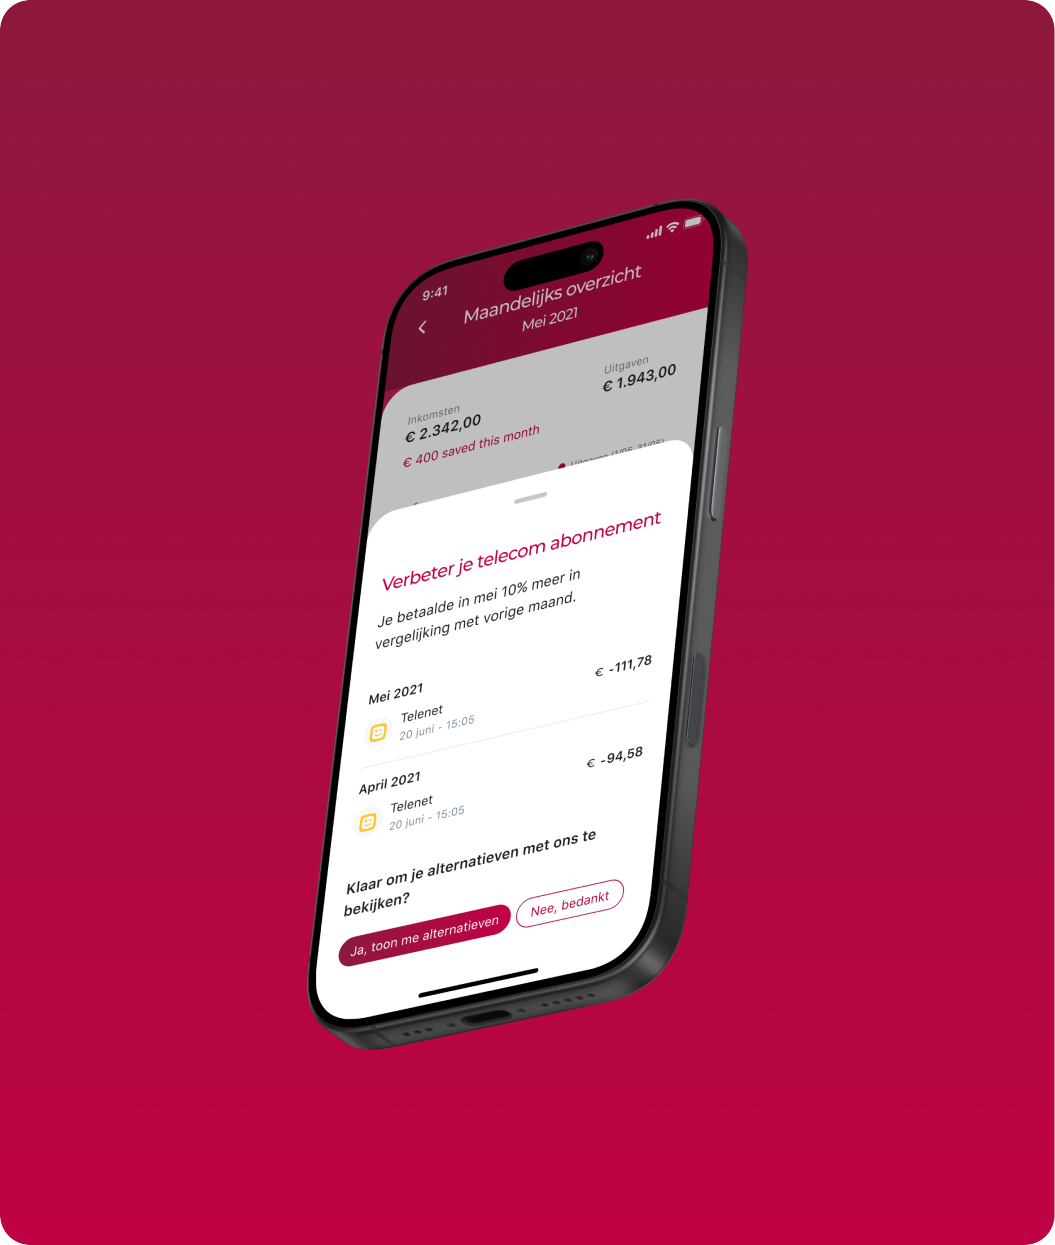
Advisor dashboard
Surfaces the right context and signals for a Belfius advisor ahead of a conversation. This lets the digital journey hand off cleanly to a human, rather than ending in a static result screen.
What the concept doesn't cover
Not a platform rebuild
The track was explicit about its limits. It does not rebuild the existing Pension Planner; it wraps and enhances it, and the job was to show exactly how the new layers plug in. It does not try to be a full financial-planning suite either.
The discipline was to do one job, coverage-ratio confidence, well, and let everything else hang off that. And it stays desirability-first: the output is a validated experience and a feasibility-aware roadmap, not a production build. One job done with real confidence does more than a sprawling tool that leaves people more anxious than when they arrived.
The THINKING
5 things that the discovery track taught us
1. Explain the number, don't just show it.
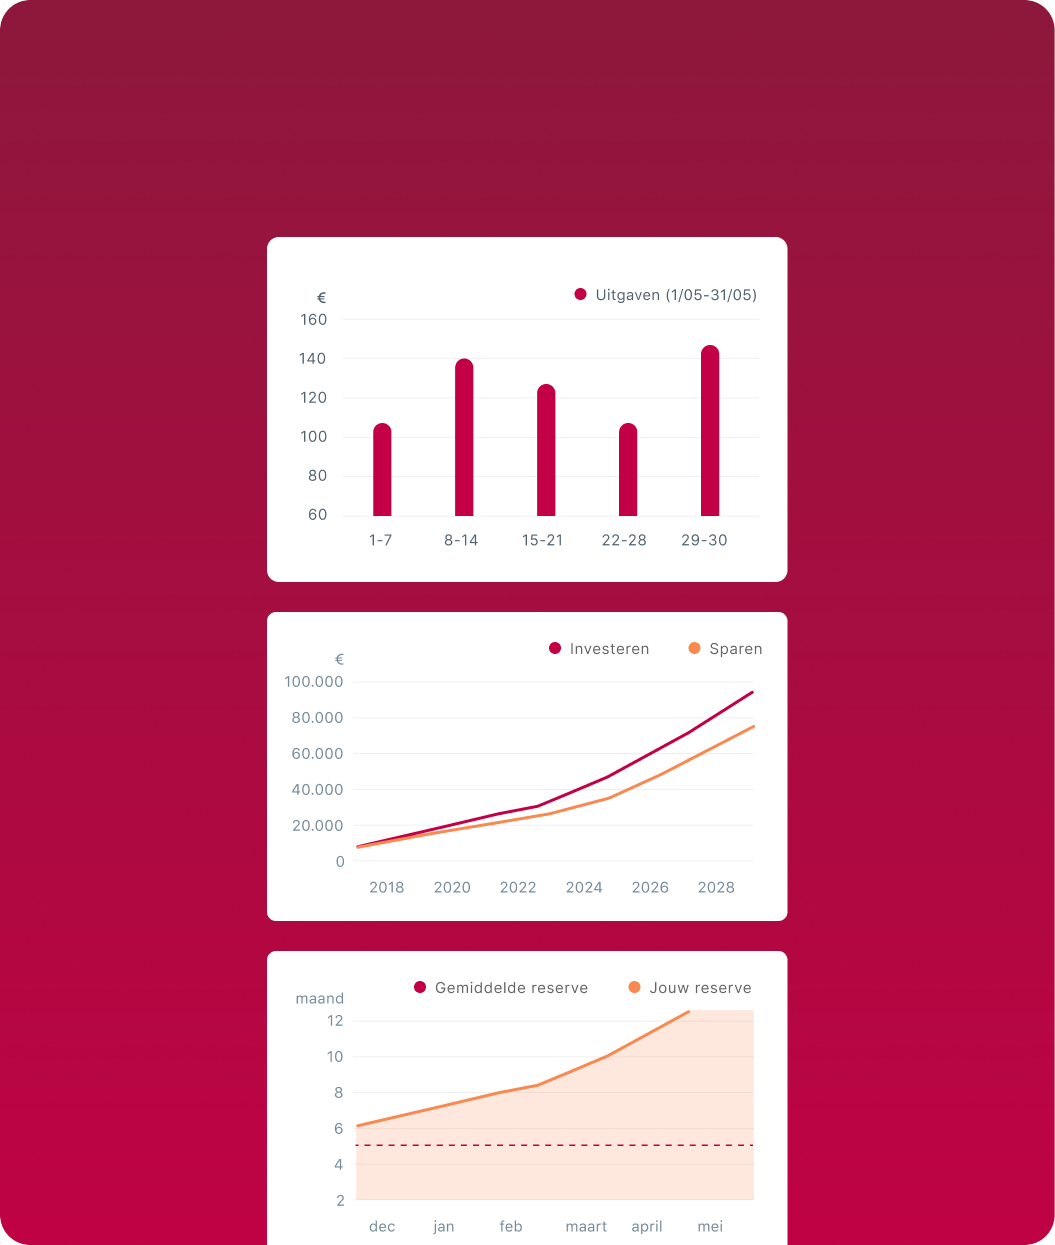
The strongest, most repeated signal was that a result without a visible rationale reads as a black box, and people do not trust what they cannot follow. In a pension setting, the explaining is the hard part and the valuable one, not the arithmetic.
2. Coverage ratio is the job to be done.
People do not want a figure; they want to know whether they will be okay. Anchoring on surplus after the life you want turns a frightening abstraction into one question a person can actually answer, and gives the business a concrete thing to design around.
3. The brand has to live in the logic, not the logo.
Belfius-specific differentiation was the decisive requirement. Data models, expense curves, and research made visible are what make the experience feel distinctly Belfius instead of a generic simulator. Without that, even a good flow reads as interchangeable.
4. Coach toward a conversation.
The digital experience's job is not to close the loop alone. It is to build enough understanding and motivation that the handoff to a human advisor feels earned and natural, which is exactly where a bank-insurer's physical distribution becomes an advantage.
5. Build beside the core, not inside it.
Developing outside the Bank's ecosystem let the team move fast without waiting on legacy priorities, while still mapping the integration back into the existing pension planner. Speed came from choosing the right place to start, not from cutting corners.
6. The hard part is alignment, not ideas.
The biggest risk in this kind of work is rarely concept quality. It is stakeholder governance: cadence, late-arriving reviewers, and split context between an insurance entity and its broader group. Lock the approver map, the working cadence, and the acceptance criteria, and bring brand and communications in early, before design starts.
Sneak peek
What's next?
The track closed on a positive note, with validated prototypes, a coverage-ratio-led flow, and a roadmap for bringing the experience into Belfius's existing pension tools. Belfius considered the mission a success and plans to take the work forward internally. That close is a launch pad, not a finish line.
The path forward is largely an internal one: aligning Belfius Insurance with the broader group, involving brand and communications early, and turning the validated experience into a build.
Beyond this first track, the same thinking, explain, coach, then hand off, extends across Belfius's wider Pension & Care ambition. This is the opening move, scoped tight on purpose, with more to explore.